
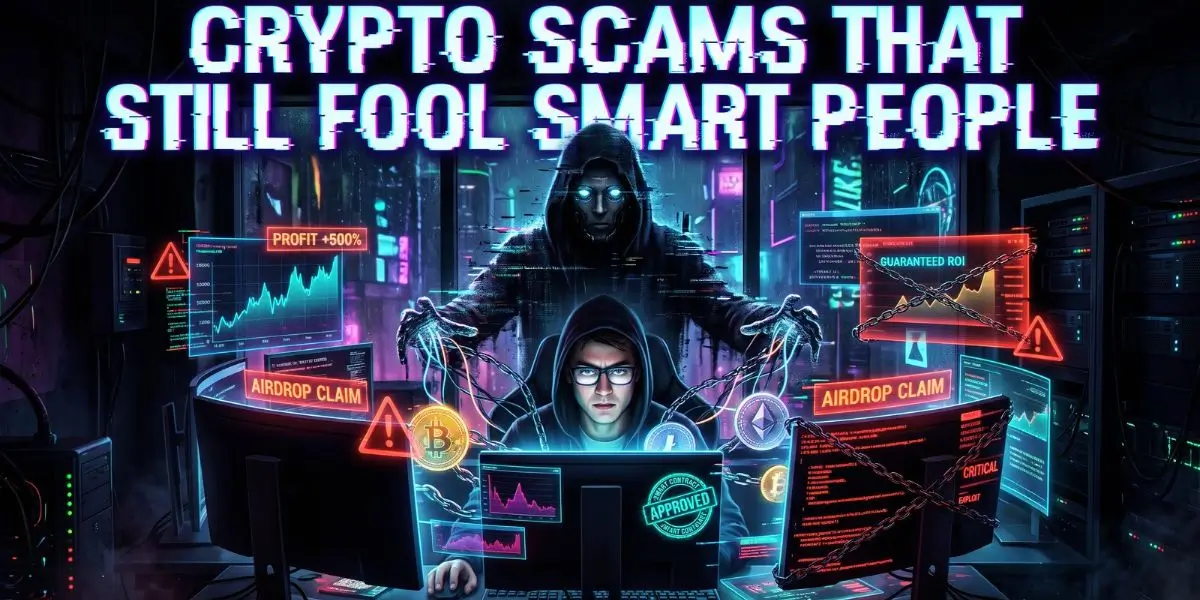
The message looked legitimate: a LinkedIn connection from a “fund manager,” a polished trading dashboard, and a 34% return in six weeks. The victim was not inexperienced. He had a finance degree, used two-factor authentication, and had read about Bitcoin for years. Yet he still wired crypto into a platform that vanished after he tried to withdraw.
Crypto scams still fool smart people because they exploit trust, urgency, social proof, and the irreversibility of blockchain transactions—not because victims lack intelligence. In 2025, the FBI’s Internet Crime Complaint Center received 181,565 cryptocurrency-related complaints and reported $11.366 billion in losses, a 22% increase from 2024.
This guide breaks down the seven scams that continue to work, explains the psychological tricks behind them, and gives you a practical defense checklist you can use before sending a single satoshi.
Why Smart People Fall for Crypto Fraud
Smart people fall for crypto fraud when a scam is designed to bypass analysis rather than overcome it. Fraudsters rarely open with “send me Bitcoin.” They begin with familiarity: a mutual connection, a plausible investment thesis, a professional-looking app, or an emergency involving an account you believe you own.
The FBI reported that cryptocurrency investment fraud alone accounted for $7.28 billion in reported losses in 2025, with an average reported loss of $62,604. Those numbers matter because they show that crypto fraud is not confined to obvious “get-rich-quick” posts. It often arrives dressed as due diligence.
The Three Levers Scammers Pull
| Lever | How it feels | What it sounds like |
|---|---|---|
| Authority | “This person knows more than me.” | “I manage a proprietary AI arbitrage fund.” |
| Urgency | “I must act now.” | “The allocation closes tonight.” |
| Social proof | “Other people are profiting.” | “My colleague withdrew $80,000 last week.” |
Pro Tip: Treat any investment opportunity that requires speed as a red flag. Legitimate investments can survive a 24-hour pause; scams often cannot.
1. Pig-Butchering and Romance Investment Scams
Pig-butchering scams are long-con relationship scams in which a fraudster builds emotional trust before directing the victim to a fake crypto investment. The U.S. Commodity Futures Trading Commission describes these schemes as relationship investment scams, sometimes involving fake identities, romance, and fraudulent crypto trading platforms.
The pattern is painfully consistent. A stranger messages you on Instagram, WhatsApp, LinkedIn, or a dating app. Conversations become daily. They share photos, talk about family, and never quite manage a video call. Eventually, they mention a trading strategy, an “uncle who works in quantitative finance,” or an exclusive crypto opportunity.
Then comes the platform. It may show profits rising. You may even withdraw a small amount once. That early withdrawal is the hook. After you invest more, withdrawals stall, “taxes” appear, or customer service demands another payment to release funds.
Red Flags
The person avoids live video calls or repeatedly cancels them.
They push you toward a specific exchange, wallet, or trading app.
The platform displays profits but blocks withdrawals.
They ask you to move funds to a different wallet for “verification,” “taxes,” or “liquidity.”
They discourage you from discussing the investment with family, friends, or a financial professional.
The U.S. Secret Service notes that a common warning sign is an online “friend” or romantic partner who cannot meet in person and avoids video calls. The FTC is even more direct: if someone you meet online offers to teach you to invest in cryptocurrency, treat it as an investment scam.
Expert Insight: The scam is not the app. The app is bait. The scam is the relationship that makes you ignore the app’s missing regulation, ownership, and withdrawal terms.
2. Fake Crypto Investment Platforms
Fake investment platforms are fraudulent websites or apps that imitate legitimate exchanges, brokers, or hedge funds to collect deposits. They often use professional branding, live charts, fake testimonials, and customer-support chat. The interface can be excellent—because building a convincing dashboard is cheaper than building a real trading business.
The FTC warns that fraudulent crypto investment sites may look real, yet victims discover they cannot withdraw the money they deposited. Some scams also impersonate celebrities or public figures with “giveaways” claiming to multiply any crypto sent to a wallet address.
How to Verify a Platform
Check the regulator database. In the U.S., search SEC, CFTC, FINRA, and state securities regulators for the entity and its registrations.
Find the legal entity. A real company should disclose a jurisdiction, registration number, physical address, and named leadership.
Test withdrawals early. Deposit the minimum amount only if you proceed at all, then attempt a withdrawal before adding more.
Inspect the domain. Look for lookalike domains such as
coinbase-support.comorbinancee.com.Search independent complaints. Search the exact platform name plus “withdrawal,” “scam,” “review,” and “regulator.”
| Legitimate platform signals | Scam platform signals |
|---|---|
| Clear corporate identity and regulatory disclosures | Vague ownership, offshore shell entities, or no legal name |
| Transparent fees, custody, and withdrawal policies | Sudden “tax,” “unlock,” or “gas” fees to withdraw |
| Independent audits and public security practices | Stock images, unverifiable “audits,” and paid testimonials |
| Support reachable through official channels | Pressure to communicate only on Telegram or WhatsApp |
| You control withdrawals | Deposits are easy; withdrawals require new payments |
3. Impersonation Scams: Exchanges, Banks, and Government
Impersonation scams occur when criminals pose as a crypto exchange, bank, wallet provider, government agency, or tech-support team to pressure you into sending crypto. The scam works because it hijacks institutions you already trust.
You might receive a call claiming suspicious activity on Coinbase, Binance, your bank, or a government benefits account. The caller may display a spoofed phone number, cite a fake case number, and tell you that the only way to “secure” your funds is to move them to a “safe wallet.” That wallet belongs to the scammer.
The FTC explicitly warns people not to transfer money, cryptocurrency, or gold in response to an unexpected call or message from someone they do not know. It also notes that scammers impersonate companies and governments, claiming an account problem or breach can only be solved by moving money into crypto.consumer.ftc+1
The Rule That Stops Most Impersonation Scams
Never move crypto because someone contacted you first. Hang up. Open the official app yourself or type the company’s website address manually. Call the number listed on the official site—not the number provided by the caller.
Pro Tip: Real support agents do not need your seed phrase, private keys, screen-sharing access, or a transfer to a “safe wallet.” Anyone asking for those is attempting theft.
4. Giveaway and Address-Poisoning Scams
Crypto giveaway scams promise to multiply cryptocurrency sent to a wallet, while address-poisoning scams trick users into sending funds to a lookalike address saved in their transaction history. Both rely on visual familiarity rather than technical sophistication.
A giveaway scam might use a hacked celebrity account, a fake livestream, or a sponsored post claiming: “Send 0.5 ETH, receive 1.5 ETH back.” No legitimate person or company needs your deposit to give money away. The FTC identifies celebrity giveaway schemes and promises to multiply crypto as common fraud tactics.consumer.ftc
Address poisoning is quieter. A scammer sends a tiny transaction from an address that looks almost identical to one you have used before. Later, when you copy an address from your history, you may select the scammer’s lookalike wallet instead. The difference can be one character buried in a long hexadecimal string.
How to Avoid Wallet-Address Fraud
Verify the full address, not merely the first and last characters.
Send a small test transaction before a large transfer.
Use an address book and confirm entries through a second channel.
Never trust a transaction history alone; scammers can seed it with lookalike addresses.
Use hardware wallets for meaningful amounts and confirm the address on the device screen.
5. Phishing, Seed-Phrase Theft, and Drainer Links
Phishing scams steal wallet access by tricking you into entering a seed phrase, signing a malicious transaction, or connecting your wallet to a fraudulent decentralized application. A single signature can authorize a drainer contract to move tokens or NFTs from your wallet.
These scams often arrive as a “security alert,” an airdrop, a mint invitation, or a customer-support reply on X, Discord, or Telegram. The attacker may create a site that looks like MetaMask, Phantom, OpenSea, or a popular DeFi protocol. The goal is simple: get you to approve a transaction that grants spending permission.
What Never to Share
Your seed phrase or recovery phrase.
Your private key.
A screenshot of your wallet’s recovery phrase.
A screen-sharing session with an unknown support agent.
A signature request you do not fully understand.
No legitimate exchange, wallet provider, or blockchain project needs your recovery phrase. If someone asks for it, end the conversation immediately.
Expert Insight: Treat every wallet signature like a bank transfer authorization. If you cannot explain what permission you are granting, reject it.
6. Rug Pulls and Fake Token Presales
Rug pulls occur when developers promote a new token, attract buyer liquidity, then abandon the project or drain the liquidity pool. Fake presales use the same playbook, but they collect funds before a token even exists.
The pitch is usually emotional: a revolutionary AI protocol, a meme coin backed by a famous influencer, an “early access” token, or a DeFi project promising impossible yields. The website may include a roadmap, whitepaper, and audit badge—but none of those guarantees liquidity, team integrity, or sustainable tokenomics.
Warning Signs of a Rug Pull
Anonymous team with no verifiable track record.
Liquidity is not locked or the lockup period is short.
A small number of wallets hold most of the supply.
The contract allows the owner to mint unlimited tokens, pause trading, or change fees.
Marketing promises guaranteed returns or “risk-free” yield.
The audit is from an unknown firm or does not match the deployed contract.
The FTC’s broader warning applies here: promises of guaranteed profits, rapid doubling, or free money are hallmarks of fraud. In crypto, “guaranteed yield” is especially suspect because returns depend on market risk, protocol risk, smart-contract risk, and counterparty risk.
7. Crypto Kiosk and “Help Me Buy Bitcoin” Scams
Crypto kiosk scams pressure victims to deposit cash into a Bitcoin ATM and send it to a scammer’s wallet, often under the guise of a government payment, tech-support fix, or emergency. The FBI reported more than 13,400 complaints involving cryptocurrency kiosks in 2025, with losses exceeding $388 million—a 58% increase in losses from 2024.
These scams often begin with a phone call: a fake IRS agent, bank investigator, Microsoft technician, or even someone pretending to be a grandchild in trouble. The caller instructs the victim to withdraw cash, insert it into a crypto kiosk, scan a QR code, and send Bitcoin. Once the transaction confirms, recovery is difficult.
Why This Scam Works
It converts familiar cash into an irreversible digital transfer.
The victim may be isolated, frightened, or told not to hang up.
The scammer provides a QR code, removing the need for the victim to understand wallets.
The story creates urgency: “Your account will be frozen,” “Your computer is compromised,” or “Your loved one needs bail money.”
If anyone tells you to buy crypto through a kiosk to pay a bill, resolve an investigation, protect an account, or help a relative, stop. That is not how banks, tax agencies, or legitimate businesses collect payment.
The Bitcoin Scammer List Problem: Why Names Alone Won’t Save You
Searching for a “bitcoin scammer list” or a specific “crypto scammer name” feels like a practical defense. It is not. The most consequential scams rarely depend on a single named individual you can look up. Pig butchering operations are run by teams using rotating personas. Fake platforms rebrand weekly. The named figures who dominate headlines—Ruja Ignatova of OneCoin, Satish Kumbhani of BitConnect, Sam Bankman-Fried of FTX—are useful case studies in how fraud scales, but they are not the people who will contact you tomorrow. Ignatova remains a fugitive; Kumbhani’s BitConnect promised impossible returns through a “trading bot” and raised $2.4 billion.
A name list cannot replace a verification habit. What protects you is a repeatable process: check the domain, verify the app developer, confirm the platform’s registration with a regulator, and refuse to send funds to any wallet you cannot independently verify. The list changes. The process does not.
How to Spot a Bitcoin Scammer: A 60-Second Checklist
You can spot most bitcoin scammers by checking four things before any money moves: the domain, the platform’s regulatory footprint, the urgency of the request, and whether anyone is asking you to keep the transaction secret.
Run this checklist before you deposit:
Domain check. Type the exchange’s name into a search engine yourself. Do not click an ad. Compare the URL character by character. A hyphen, an extra letter, or a different top-level domain is enough.
Regulatory check. Look up the platform on the regulator’s public register—FinCEN, FCA, ASIC, or your national securities authority. A license number is meaningless unless the register confirms it.
App check. Confirm the developer name matches the company’s official website. Check whether the app’s privacy policy and support channels are coherent.
Urgency check. Legitimate investments do not require you to decide in minutes. Countdown timers, “last chance” bonuses, and callers who refuse to let you hang up are pressure tactics, not opportunities.
Secrecy check. If anyone tells you not to discuss the investment with your family, your bank, or an advisor, the reason is that an outside perspective would break the spell.
Withdrawal test. Before scaling a deposit, make a small withdrawal. If the platform delays, invents fees, or blocks the request, stop immediately.
Crypto Scams: How to Get Money Back (And What to Do in the First Hour)
Recovering crypto after a scam is difficult and never guaranteed, but the first 24 hours determine whether any funds can be preserved, frozen, or traced. Blockchain transactions are generally irreversible once confirmed, but exchanges can sometimes freeze identified wallets, and banks can sometimes reverse the fiat purchase that funded the crypto.
Here is the sequence that gives you the best possible position:
Step 1: Contain the damage immediately. If you shared a seed phrase or private key, move any remaining assets to a new wallet right now. Disconnect your wallet from any malicious site. Revoke token approvals using Revoke.cash or Etherscan’s Token Approval Checker.
Step 2: Stop all contact with the scammer. Do not send another dollar to “unlock” a withdrawal. Do not negotiate. Every additional payment is treated as confirmation that you are still in the funnel.
Step 3: Document everything. Save transaction hashes, wallet addresses, screenshots of the platform, chat logs, emails, and the dates and amounts of every transfer. This evidence is what investigators and exchanges actually use.
Step 4: Report to your exchange and your bank. If the funds moved through a centralized exchange, contact its fraud team with the transaction details. If you purchased crypto with a debit or credit card, ask your bank about a chargeback on the purchase itself—not on the transfer to the scammer.
Step 5: File with law enforcement and regulators. In the U.S., report to the FBI’s IC3 at ic3.gov and the FTC at reportfraud.ftc.gov. FinCEN’s Rapid Response Program and the FBI’s Operation Level Up have been used to notify victims and reduce losses, but early reporting is the variable that matters most.
Step 6: Treat recovery offers with suspicion. The overwhelming majority of services that promise to retrieve your crypto for an upfront fee are secondary scams. Legitimate blockchain analysis firms work with law enforcement, not as cold-calling recovery agents.
Reality check: There is no guaranteed way to get crypto back from a scammer. Anyone who guarantees recovery is selling you a second scam. The realistic goals are preserving remaining assets, freezing what can be frozen, and building a record that helps investigators disrupt the operation.
Case Study: How a $12,000 Scam Unfolded
Consider a composite case based on common FBI and FTC reporting patterns. Maria, a 42-year-old nurse, received a LinkedIn message from “Daniel,” who claimed to run a crypto arbitrage desk. They spoke daily for six weeks. He never asked for money directly. Instead, he invited her to “observe” his trading dashboard.
The dashboard showed a balance growing from $500 to $780. Maria withdrew $80 successfully. Encouraged, she deposited $12,000 over three transactions. When she tried to withdraw, the site demanded a 10% “anti-money-laundering fee.” Daniel said it was standard. She paid. Then the site demanded another fee. Daniel disappeared, and the domain went offline.
The lesson is not that Maria was careless. The scam used small wins to establish credibility, then used withdrawal friction to extract more money. A verification habit—checking the company registration, refusing unsolicited investment advice, and treating a withdrawal fee as a dealbreaker—could have stopped the loss earlier.
How to Protect Yourself: A 10-Point Checklist
Use this checklist before you send crypto, connect a wallet, or invest in a new platform.
Pause for 24 hours. Urgency is a manipulation tactic.
Verify the person independently. Do not rely on their profile, references, or screenshots.
Never share your seed phrase or private key.
Check regulatory registrations through official government databases.
Confirm the website domain character by character.
Start with the smallest possible amount and test a withdrawal.
Reject withdrawal fees demanded after you try to cash out.
Use a hardware wallet for significant holdings.
Separate trading funds from long-term savings.
Discuss unusual investments with someone outside the chat.
If You Have Already Been Scammed
Act quickly, but be skeptical of “recovery agents.” Many secondary scams target victims by promising to recover stolen crypto for an upfront fee.
Stop sending money. Do not pay “release,” “tax,” or “verification” fees.
Save evidence: wallet addresses, transaction hashes, screenshots, chat logs, emails, domain names, and payment records.
Revoke wallet permissions using a reputable token-approval tool, then move remaining assets to a fresh wallet.
Report the crime to your local police, national cybercrime authority, and relevant financial regulator.
Report to the FBI’s IC3 if you are in the United States; its 2025 report shows cryptocurrency fraud remains a major enforcement priority.
Warn the platform if the scam impersonated a legitimate exchange or brand.
Avoid unsolicited recovery services. Verify any firm independently before paying anything.
FAQs
What is the most common crypto scam?
Cryptocurrency investment fraud is among the most damaging categories. The FBI reported $7.28 billion in investment-fraud losses tied to cryptocurrency in 2025.ic3
Can stolen crypto be recovered?
Sometimes, but recovery is difficult and never guaranteed. Blockchain transactions are generally irreversible, and criminals may quickly move funds through mixers, exchanges, or cross-chain bridges. Be especially cautious of anyone promising guaranteed recovery.
How do I know if a crypto platform is fake?
Look for unverifiable ownership, missing regulatory disclosures, withdrawal blocks, new “fees,” pressure to use Telegram or WhatsApp, and promises of guaranteed returns. The FTC warns that fake platforms can look real while preventing withdrawals.
No. Never share your seed phrase, recovery phrase, or private key. No legitimate exchange, wallet provider, or support agent needs it.
What should I do if someone asks me to use a Bitcoin ATM?
Do not do it if the request comes from an unexpected caller, text, email, or online contact. The FBI reported more than $388 million in 2025 losses connected to crypto kiosks.
Are crypto giveaways real?
Almost never. If someone asks you to send crypto first in order to receive more back, it is a scam. The FTC identifies such “multiply your crypto” giveaways as fraudulent.
Can crypto transactions be reversed after a scam?
Generally, no. Blockchain transactions are processed by a decentralized network and are not reversible once confirmed. The narrow exception is a centralized exchange that still controls the receiving account and chooses to intervene in a clear fraud case.
Is a fake crypto trading website ever obvious?
Sometimes, but not always. Many clones are visually identical to the real platform. The most reliable tells are the domain name, the lack of verifiable regulatory registration, and withdrawal friction. A platform that accepts deposits instantly but invents fees when you try to withdraw is not a platform—it is a collection mechanism.
How do I check if a crypto app is legitimate?
Verify the developer name against the company’s official website, read the app’s permission requests, and search for independent security reviews. A store listing alone is not proof; fake apps have appeared on both Google Play and the App Store.
What is a fake crypto simulator used for?
It is used to create the appearance of real trading activity. The simulator generates fake interfaces, fake transaction histories, and fake profits that never touch a blockchain. The defense is to verify every transaction hash on a public explorer outside the platform’s own interface.
Where can I find a free list of fake crypto trading websites?
Regulators publish blacklists and warning lists at no cost. Check the FCA’s warning list, ASIC’s investor alerts, Belgian FSMA’s fraud list, and your state securities regulator. These lists are useful but incomplete; new domains appear constantly, so pair the list with domain verification.
The Only Advantage You Need
Margaret’s scammer did not outsmart her. He outlasted her caution. The platform did not hack her wallet. It gave her a story she wanted to believe, and then charged her for the privilege.
The seven scams in this guide are variations on one theme: someone asks you to move money before you have independent verification. The defense is not cynicism. It is a procedure. Check the domain. Verify the registration. Test the withdrawal. Refuse secrecy. And if you have already been caught, act in hours, not weeks—document, report, and do not pay a second stranger to fix what the first stranger broke.
The best time to run the checklist is before the first deposit. The second-best time is right now.
Next Steps
Protecting your crypto starts with one habit: slow down before you sign, send, or deposit. Verify the platform, refuse unsolicited investment offers, safeguard your seed phrase, and treat every urgent request as a potential attack. If you recognize even one red flag, stop and get a second opinion from a trusted person or a regulated professional.